Box sets » Economic and fiscal outlook - November 2025
In this box, we explained how block grant adjustments are calculated for Scotland and Wales. We also explore the rationale behind these tax devolution arrangements and how this impacts the Scottish and Welsh budgets.
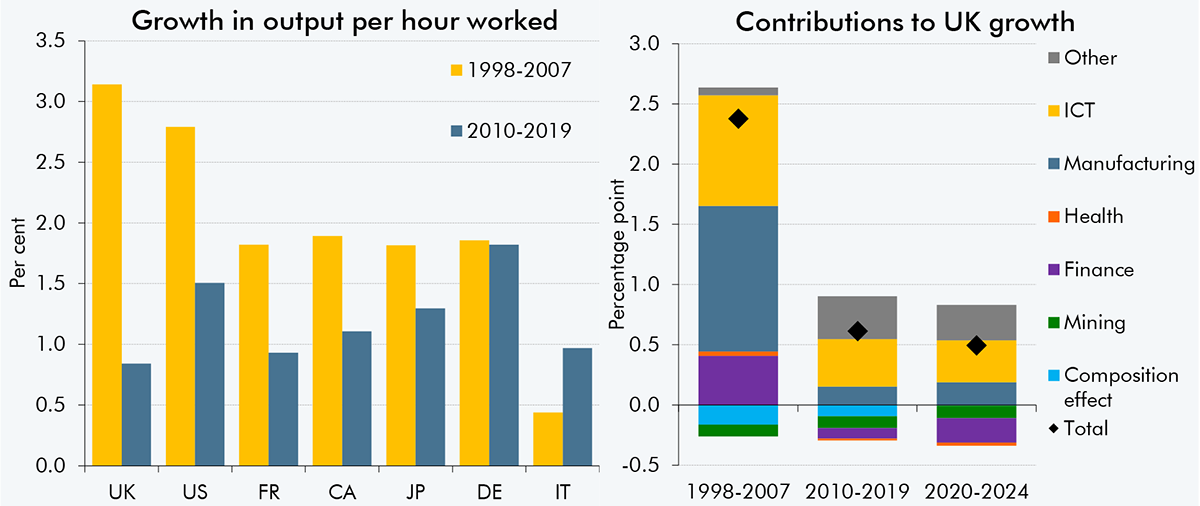
The likely rate of productivity growth is one of the most important judgements in our economic and fiscal forecasts. Alongside this EFO, we have published Briefing paper No. 9: Forecasting productivity, which sets out our latest view of trend productivity growth. This box set out key findings from the paper and scenarios for future productivity growth.
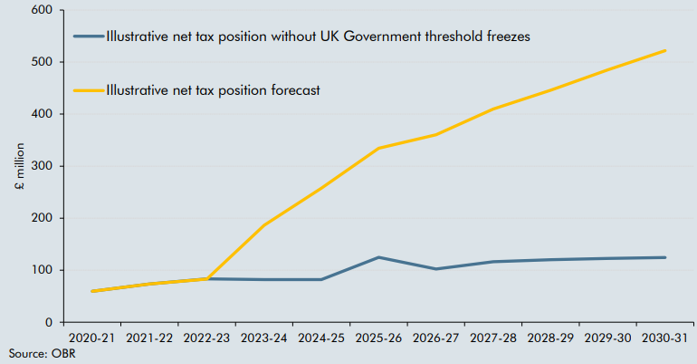
The UK Budget saw the extension of the personal tax threshold freezes. This box looked at the projected impact of the threshold freezes on the net tax position in Scotland and Wales.
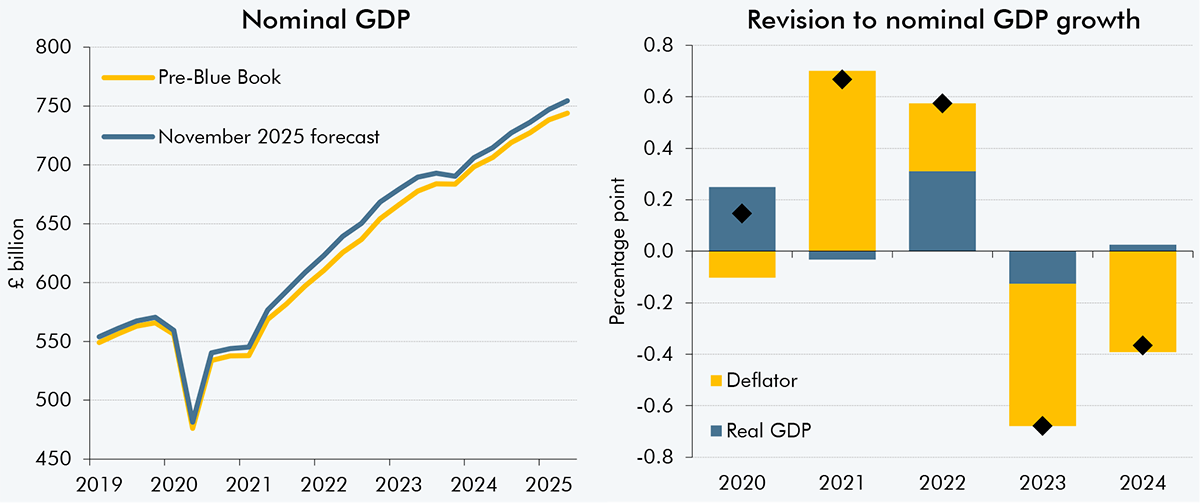
The Quarterly National Accounts published on 30 September by the ONS included revisions consistent with Blue Book 2025, which we have incorporated into our forecast. This box explored what these revisions were and their impact on our forecast. While the revisions to the starting level have not changed our view about the outlook for overall GDP growth, the compositional changes have contributed to our forecast judgements.
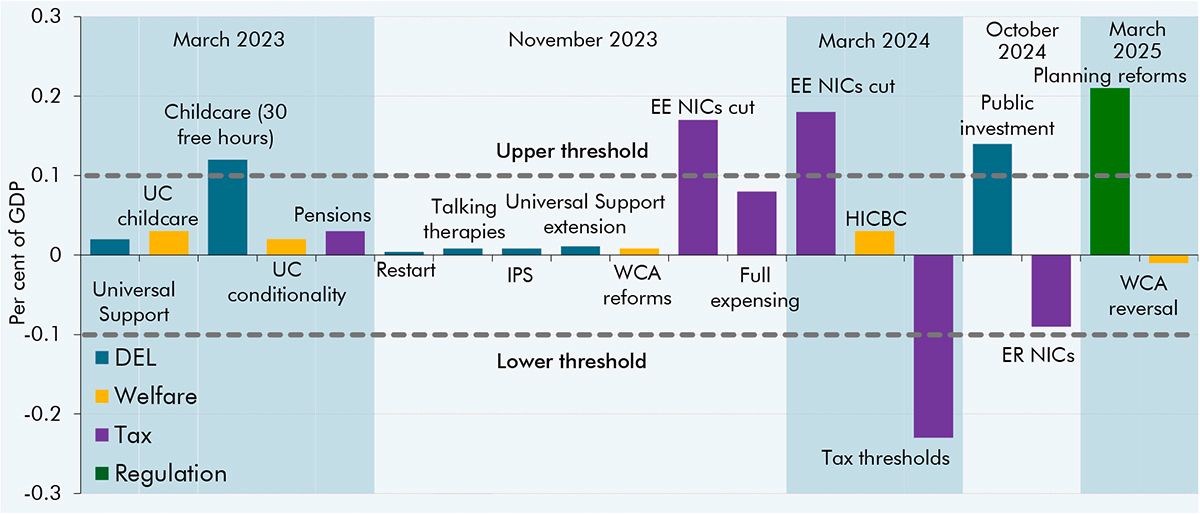
We have taken a more transparent approach to accounting for the supply-side impacts of policy over the past three years. This box summarised the findings and conclusions from Briefing Paper No. 10: Accounting for the supply-side effects of policy, published alongside the November 2025 Economic and fiscal outlook, which reviews our approach to incorporating such effects into our forecast.
In the March 2025 Economic and fiscal outlook, we were unable to assess the economic effects of certain elements of the Pathways to Work Green Paper that had been incorporated into our fiscal forecast, as the Government had not provided sufficient information at that time. We have now related the full assessment of these policies in this box.
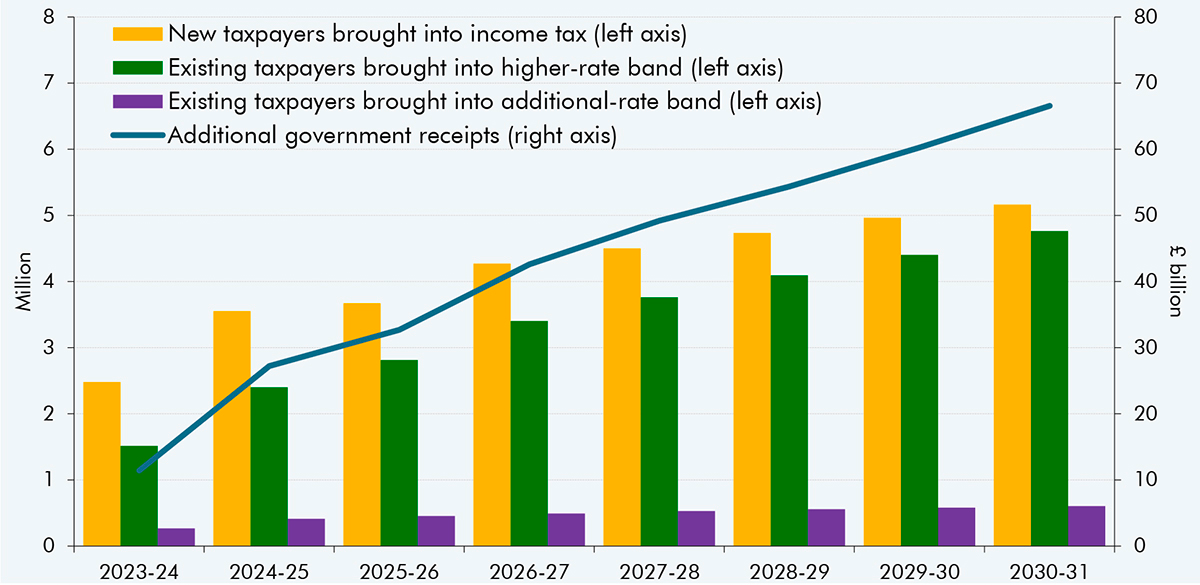
This Budget has extended the allowances and threshold freezes in income tax and National Insurance Contributions (NICs) to the end of the forecast period. In this box we explored the overall impact of threshold freezes since 2022-23 on additional taxpayers and tax receipts.
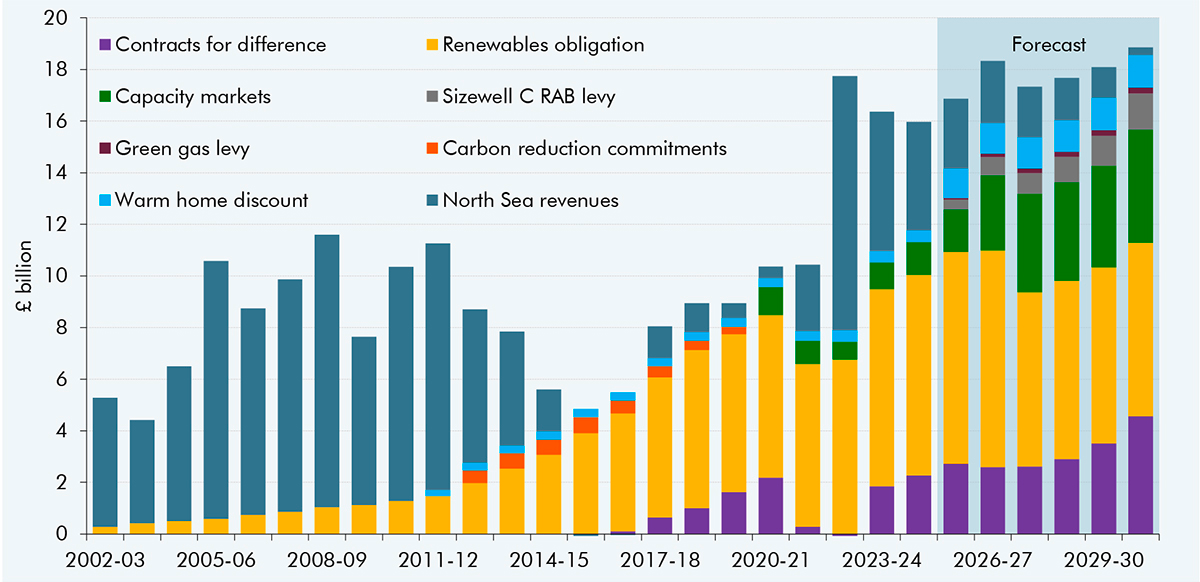
Environmental levies on household energy bills have been increasing reflecting a shift away from the taxation of energy extraction to taxation on the consumption of energy. In this box, we considered some of these schemes and how they have been impacted by Government policy at this event.
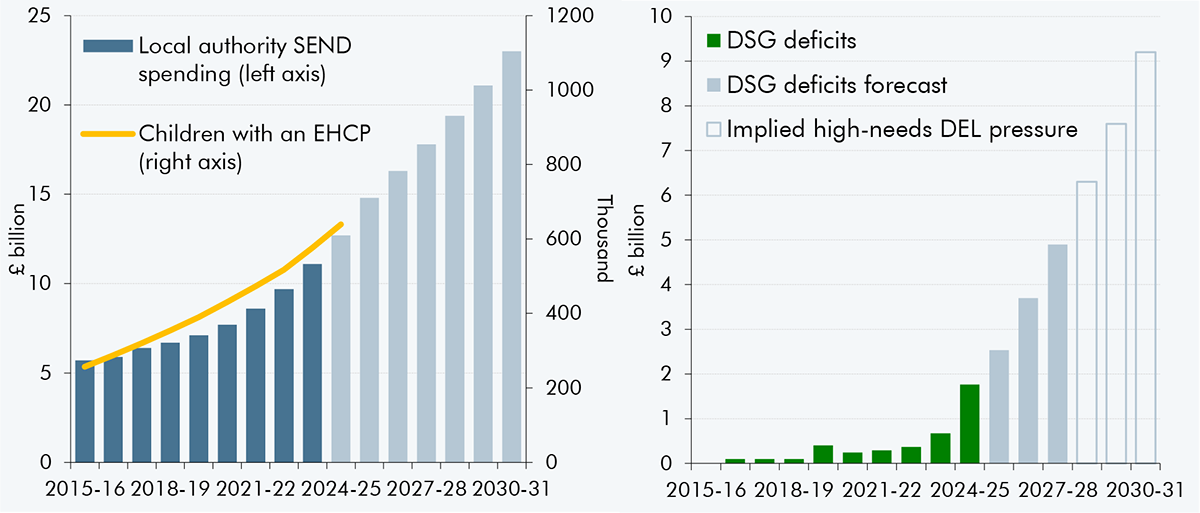
Local authorities continue to face significant cost pressures providing for special educational needs and disabilities. In this box, we explored the scale of this cost pressure, how we expect it to evolve over time, and the fiscal implications to local and central government.
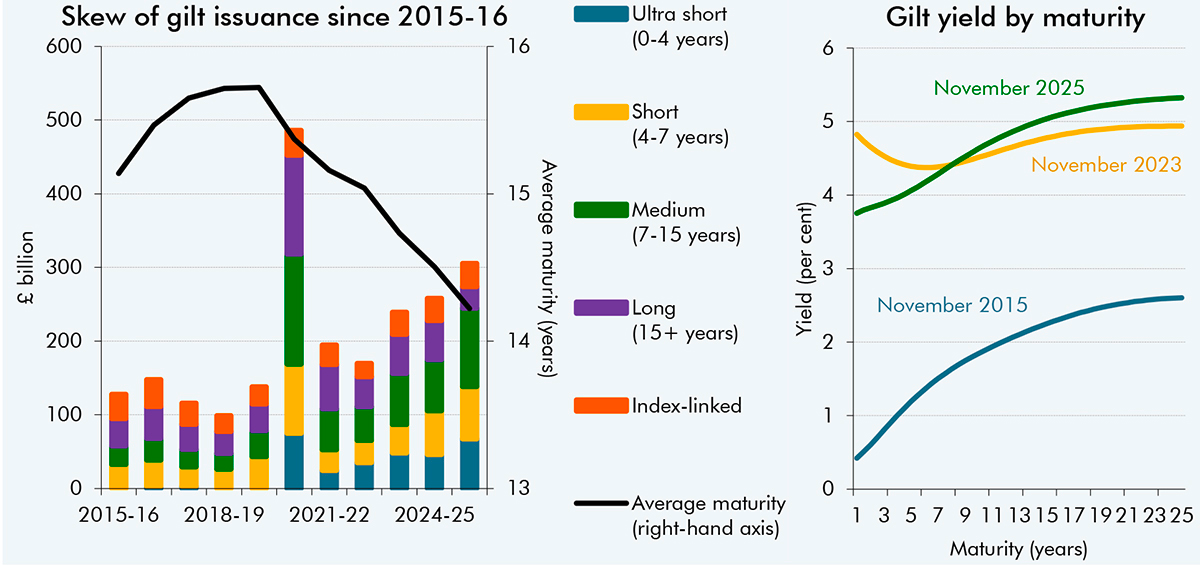
The composition of gilts issued by the Debt Management Office in recent years has become more skewed toward shorter maturities. In this box, we explored the implications of a lower average maturity of UK marketable debt.
In this box, we explained how block grant adjustments are calculated for Scotland and Wales. We also explore the rationale behind these tax devolution arrangements and how this impacts the Scottish and Welsh budgets.
The UK Budget saw the extension of the personal tax threshold freezes. This box looked at the projected impact of the threshold freezes on the net tax position in Scotland and Wales.