This Forecast in-depth page has been updated with information available at the time of the March 2026 Economic and fiscal outlook.

In this section:

  • Current account balance – the sum of the balance of trade, balance of investment income, balance of transfers, and balance of employee income
  • Trade balance – the balance of nominal exports and nominal imports
  • Income account balance – the balance of the income the UK generates on its overseas investments and the income it pays overseas investors who own UK-based assets
  • Transfers balance – the balance of various transfers to and from abroad
  • Employee income balance – the balance of employee compensation from abroad and employee income due abroad

We construct our forecast for the current account balance in a bottom-up way by projecting these component balances.

The UK has run a large current account deficit for the past couple of decades. We forecast this to continue over the next five years, with substantial deficits across the trade, transfers and investment income balances.
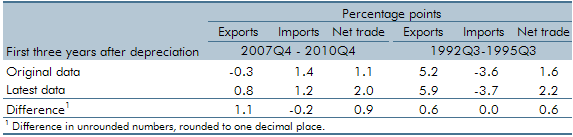
  Trade balance

The trade balance equals the value of exports less the value of imports – covering both goods and services. Our forecasts for the value of exports and imports combine our forecasts for real exports and imports with our forecasts for the export and import deflators (measures of the prices of exports and imports). The ratio of the export deflator to the import deflator is known as the ‘terms of trade’ – an indicator of how much a country can afford to import by selling a given volume of exports.

  Back to top

  Income account balance

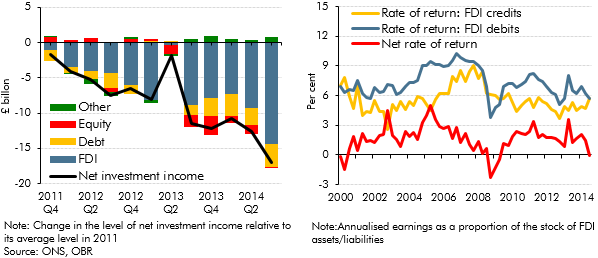
The income account balance is equal to the credits the UK generates on its overseas investments (‘assets’), less the debits it pays overseas investors who own UK-based assets (‘liabilities’). Our approach to forecasting credits and debits involves two steps:

  • First, we forecast the stock of overseas assets and liabilities. The change in the value of the stocks of assets and liabilities reflects both revaluation effects and the net acquisition of those assets and liabilities. Our forecasts for revaluations include the effect of exchange rate movements. We forecast the net acquisition of assets and liabilities using behavioural equations on our macroeconomic model.
  • We then forecast the associated effective rate of return on those assets and liabilities. These forecasts are informed by equations from our macroeconomic model, but will also involve a layer of staff and BRC judgement based on the latest evidence. The forecasts therefore reflect several factors, including relative interest rates domestically and overseas, movements in the exchange rate, and changes in domestic and global equity prices.

Taken together, these elements provide a forecast for the income credits from UK assets abroad and the income debits from UK-based assets held by overseas investors.

  Back to top

  Transfers balance

The UK makes and receives various transfers to and from international organisations. Our forecasts for these transfers are largely based on our forecast for the public finances. On top of these flows, overseas households send transfers to the UK, which we assume grow in line with our major trading partners’ GDP. And UK households send transfers abroad, which we forecast in line with UK wages and salaries growth.

  Back to top

  Employee income balance

The employee income balance is a relatively small component of the current account and is equal to employee compensation from abroad less employee income due abroad. We assume employee compensation from abroad grows in line with GDP growth in our major trading partners, while employee income due abroad follows our forecast for UK compensation of employees.

  Back to top

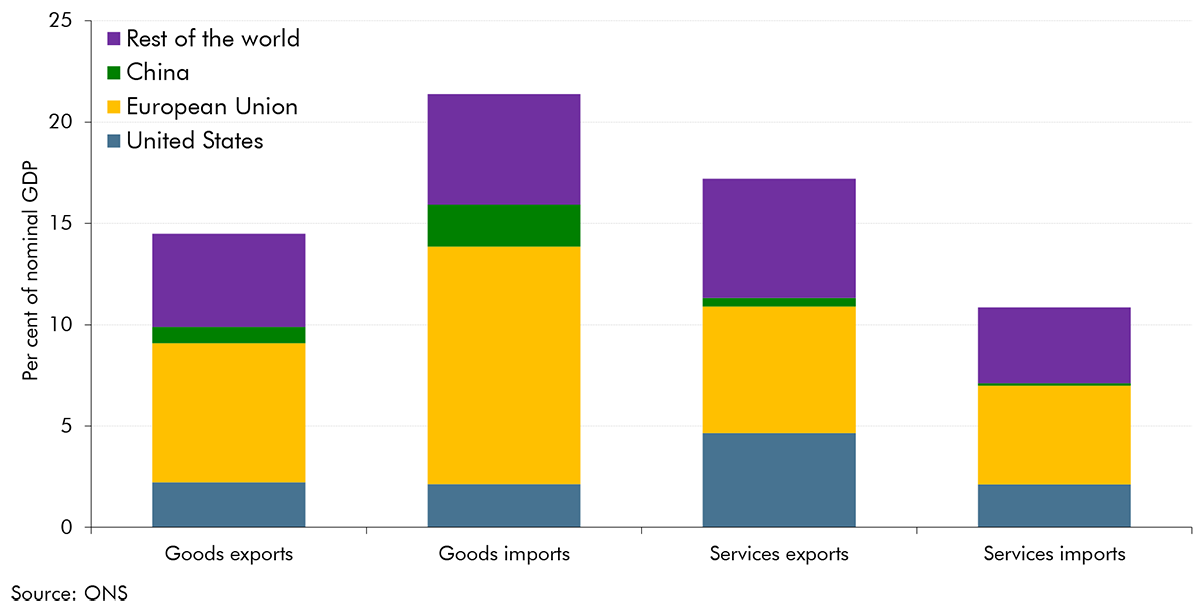
Stacked bar chart showing the composition of UK trade in 2023
In the run-up to our March 2025 Economic and fiscal outlook, global trade policies had been subject to frequent changes and the future direction for trade policy was highly uncertain. In this box, we outlined three illustrative scenarios to show the potential impact of higher US and global tariffs on UK output and inflation, highlighting the primary transmission channels and their probable effects.