Welsh rates of income tax receipts in 2023-24 were higher than forecast. In this box, we assessed the reasons for this forecast difference.
This box is based on OBR data from January 2026 .
HMRC published 2023-24 outturn data for the Welsh rates in July 2025. Assessing the performance of our forecasts is important for transparency and accountability, while also helping us to understand and identify ways to improve them. In this box, we evaluate our forecast from the December 2022 WTO, which formed the basis of the revenue projections for the 2023 Welsh draft and final budget.
The December 2022 WTO forecast was produced against the backdrop of high inflation and rises in interest rates following the energy-price shock triggered by Russia’s invasion of Ukraine. The forecast drew on the UK-wide economic projections set out in the November 2022 EFO, the 2019-20 Survey of Personal Incomes, UK-wide PAYE outturn data from 2020-21, and RTI data from August 2021.
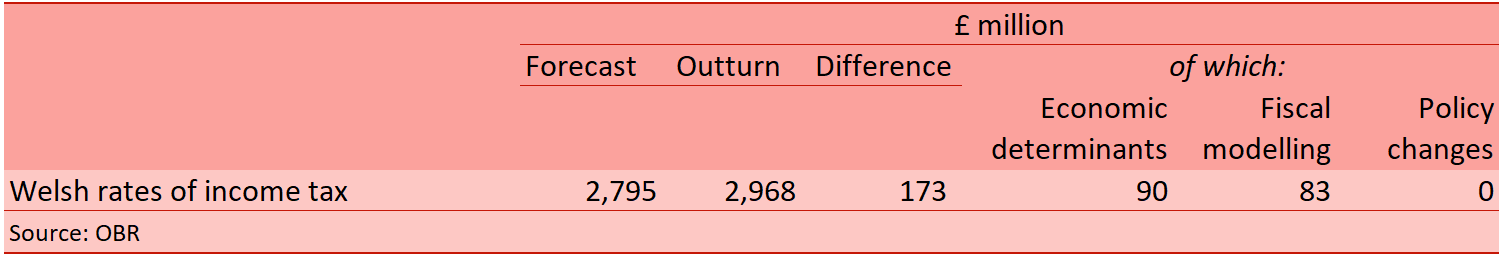
Table A shows that Welsh rates of income tax outturn in 2023-24 exceeded the December 2022 forecast by £173 million (6.2 per cent). This is the second largest one year ahead forecast difference since we began forecasting Welsh rates. The £173 million difference can be attributed to three factors:
- Economic determinants account for £90 million of the difference between our December 2022 forecast and outturn, just over half of the overall error. This reflects stronger than expected nominal earnings and employment growth in our UK-wide forecast that underpinned the December 2022 projections. We forecast growth in wages and salaries of 3.3 per cent for 2023-24, compared with eventual outturn of 7.6 per cent. This was driven in particularly by stronger nominal earnings growth, which was 6.9 per cent in 2023-24 compared to our forecast of 3.5 per cent.
- Fiscal modelling differences contribute £83 million, just under half of the overall difference. Part of this (£18 million) is driven by an underestimate of the Welsh share but the majority relates to underestimating the effective tax rate in our overall UKNSND
forecast. This may reflect greater-than-expected fiscal drag, with more taxpayers moving into, or further into, the higher and additional rates than anticipated at the time of the forecast. This could have been driven by the stronger nominal pay growth noted above, alongside frozen income tax thresholds, which together raised the effective tax rate by more than expected. It may also reflect distributional differences in earnings growth relative to those we assumed in our December forecast – in particular, stronger growth in high-income earners and bonuses than expected. - The difference relating to subsequently announced policies is small, at £0.2 million.
Table A: The Welsh rates of income tax in 2023-24: forecast versus outturn
Since the December 2022 forecast, we have made a number of improvements to our forecasting models to raise their accuracy. In particular, for our UKNSND forecast, we now explicitly allow
for the persistence of the recent ‘U-shaped’ pattern in earnings growth across the distribution (higher pay growth at the bottom and top of the income distribution), rather than assuming convergence to a uniform rate over the forecast horizon. We also now separately model bonuses by sector, linking bonuses in financial services to recent share price movements. This was based on work looking at the historical differences in the distribution of earnings.a These methodological changes aim to better capture distributional earnings dynamics and bonus behaviour. For our forecasts of the Welsh share, we now make greater use of HMRC real-time information data, looking at RTI by income tax band. This allows us to draw on more timely evidence on distributional differences between Wales and the rest of the UK.
This box was originally published in Welsh taxes outlook – January 2026