This Forecast in-depth page has been updated with information available at the time of the March 2026 Devolved tax and spending forecast.

Aggregates levy is a tax on the commercial exploitation of rock, sand and gravel. Aggregates levy has been devolved to Scotland, and Scottish aggregates tax (SAT) came into effect in April 2026. Revenue Scotland administer this tax.

SAT applies to the commercial exploitation of rock, sand and gravel in Scotland, and materials mixed with these at the time of extraction. SAT is due from any business that quarries, dredges or imports these products.
  Rates

In 2026-27, SAT rates will align with the UK aggregates levy. This is because the block grant adjustment (BGA) baseline for SAT will be calculated using outturn data from the first year of devolution, rather than the year prior to devolution. This is due to the Scotland-specific outturn data for the UK aggregates levy not being available for the year prior to devolution, with Scotland and rest of UK specific outturn data needed to set a baseline for the BGA. For future years, it is assumed that SAT rates are uprated in line with RPI.


  Back to top

  Methodology

Our forecast for Scottish aggregates tax (SAT) follows the model developed and operated by the Scottish Fiscal Commission (SFC). We estimate Scotland’s share of UK aggregates levy receipts according to the proportion of aggregates commercially exploited in Scotland. This is then projected forward based on the historical trend in aggregate tonnage in Scotland. Our forecast for RPI inflation is used to uprate the SAT rate each year.

As there is not yet any outturn data for SAT, we draw on analysis produced by the SFC to construct an estimated historical Scottish aggregates series. The SFC’s approach estimates Scotland’s share of annual taxable tonnage using production data from the UK Minerals Yearbook, with adjustments for imports and exports using evidence from the Aggregate Minerals Survey. These annual estimates are then converted into quarterly figures using HMRC outturn data. The resulting series is de-seasonalised and projected forward, before seasonal patterns are re-applied to generate forecast tonnage.

Receipts are calculated by applying the aggregates tax rate to this projected tonnage. The rate of SAT is uprated using our forecast for RPI inflation. Lastly, the receipts are scaled down to reflect reliefs and exemptions using HMRC’s outturn data for the UK.

We will develop this methodology further once we have outturn data for SAT receipts.

  Back to top

  Latest forecast

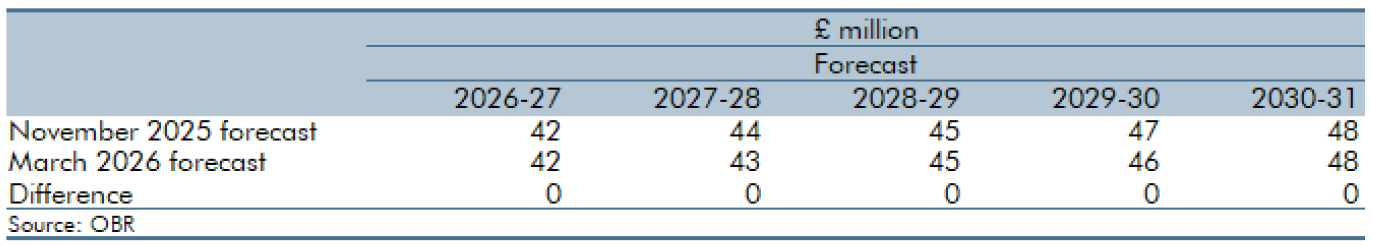
Our latest forecasts for Scottish aggregates tax were published in March 2026 and are shown in the table below. The forecast was largely unchanged since the November 2025 budget. Scottish aggregates tax revenues increase over the forecast by an average of £1.5 million annually, reflecting RPI uprating and historical growth in the exploitation of Scottish aggregates.

Table 1: Scottish aggregates tax

Table showing Scottish aggregates levy tax

  Back to top

Other devolved taxes